
 by
If you have been searching for bank rented property for sale in Karachi, you already understand the core appeal: a commercial unit occupied by a Tier-1 bank delivers something that most real estate assets in Pakistan simply cannot — a contractually obligated, institutionally backed rental income stream that arrives on the first of every month without a single phone call to a defaulting tenant. In Karachi’s 2026 commercial market, where standard retail vacancies are rising in secondary corridors and residential yields remain compressed between 5% and 7%, bank-leased commercial properties are generating net yields of 8% to 10% per annum — a meaningful premium for investors who understand how to evaluate, price, and legally structure the acquisition correctly.
This guide is not a generic overview. It is a field-tested advisory framework built from MaxX Capitals’ direct experience negotiating bank-branch lease assignments, inspecting commercial units across DHA Phase 5, Phase 6, Clifton Block 5, and Gulshan-e-Iqbal, and modeling gross-to-net yield compression for investors with capital ranging from PKR 3.5 crore to PKR 25 crore. By the time you finish reading, you will know exactly how to calculate real yield, what lease clauses can destroy a deal, which corridors offer the strongest returns in 2026, and precisely what the tax and regulatory framework costs you at acquisition and exit.
Key Takeaways (Executive Summary)
Primary Insight: Bank-rented commercial properties in Karachi’s prime corridors (DHA Phase 5/6, Clifton Block 5) are generating gross yields of 9%–12% and net yields of 8%–10% in 2026, after withholding tax and maintenance deductions.
Financial Impact: On a PKR 4.5 crore ground-floor unit rented at PKR 180,000/month, net annual return after FBR Section 155 withholding and costs settles at approximately PKR 360,000–PKR 396,000 net of tax — with a 10% annual escalation clause compounding income over a 5-year lease.
Legal / Due Diligence Check: The single most critical legal point is the lease assignment clause — many bank leases are non-transferable to a new owner without the bank’s written consent, meaning you could purchase a property and lose the tenant on day one.
Actionable Recommendation: Investors with PKR 4 crore to PKR 15 crore in deployable capital, active tax filer status, and a 5–10 year holding horizon are the strongest candidates for this asset class. Those seeking short-term capital gains should look elsewhere.
Table of Contents
1. Why Bank-Rented Properties Attract Serious Investors in Karachi
The Institutional Tenant Advantage
Not all commercial tenants are equal. A private retailer, a pharmacy chain, or a restaurant occupying your ground-floor unit brings market-rate rent — but also brings vacancy risk, fit-out damage, delayed payments, and the perpetual possibility of a dispute at lease renewal. A bank branch is categorically different.
Pakistani commercial banks — HBL, MCB, UBL, Bank Alfalah, Meezan Bank, and their peers — are regulated entities under the State Bank of Pakistan (SBP). They carry investment-grade credit profiles, maintain dedicated facilities management teams, and invest PKR 15 lakh to PKR 40 lakh of their own capital into branch fit-outs (vault installations, ATM infrastructure, security systems, and branded interiors). That fit-out investment creates a powerful retention incentive: banks do not vacate lightly because relocation costs are enormous.
💡 Tenant Quality Differentiators at a Glance
How Predictable Rental Income from a Bank Compares to Other Tenants
In Karachi’s current commercial market, standard retail units in DHA Phase 6 or Clifton Block 5 yield between 7% and 9% gross — but vacancy periods between tenants average 3 to 6 months, and rent negotiations at renewal are contentious. Office tenants in mid-tier buildings along Shahrah-e-Faisal yield 8%–10% gross but carry higher maintenance obligations and more frequent tenant turnover.
Bank-rented properties trade at a capital premium precisely because the market prices in the certainty of income. A unit that would yield 10% gross with a private tenant might yield 9% gross with a bank tenant — but the bank-rented unit commands a 10%–15% higher asking price because the income is contractually secured for 5 to 10 years with built-in escalation. For investors prioritizing income stability over maximum yield, this trade-off is rational and well-supported by transaction evidence in Karachi’s 2025–2026 market.
2. Where Bank-Rented Properties Are Actually Available in Karachi
Primary Commercial Corridors
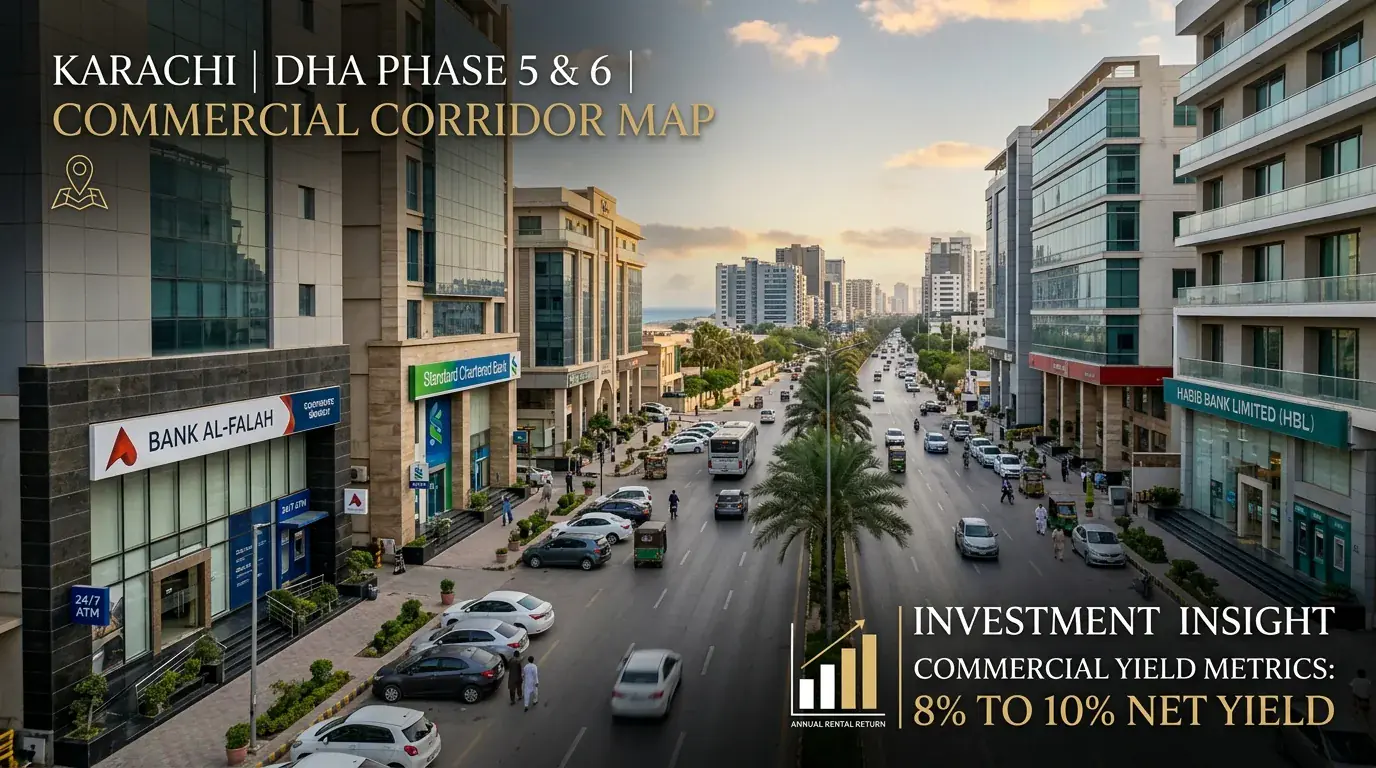
The highest concentration of bank-rented commercial properties for sale in Karachi clusters in three primary corridors where branch density, foot traffic, and institutional demand converge:
DHA Defence (Phases 4, 5, 6, and 8): The DHA commercial strips — particularly the Phase 5 Bukhari Commercial, Phase 6 Badar Commercial, and Phase 8 Broadway Commercial — host the densest concentration of bank branches in Karachi outside the CBD. Ground-floor units here range from 800 sq ft to 2,500 sq ft. Asking prices for bank-occupied units currently range from PKR 4.5 crore to PKR 18 crore depending on size, remaining lease term, and bank tier. Gross yields range from 9% to 11%. For verified listings across DHA’s commercial corridors, MaxX Capitals maintains an active inventory at DHA Karachi Properties & Commercial Plots.
Clifton Block 5 and Block 9: The Zamzama Boulevard and Clifton Block 5 strip is one of Karachi’s most premium commercial addresses. Bank branches here — particularly HBL, Meezan, and MCB flagship branches — occupy ground-floor units in purpose-built commercial buildings. Asking prices range from PKR 6 crore to PKR 22 crore for bank-occupied units. Gross yields compress to 8%–9.5% due to the capital premium on the address. Detailed corridor analysis is available at Clifton Karachi Real Estate & Commercial Properties.
Gulshan-e-Iqbal Main University Road: A high-footfall corridor serving Karachi’s largest middle-income catchment. Bank branches here occupy both ground-floor units in commercial plazas and standalone buildings. Asking prices range from PKR 2.8 crore to PKR 8 crore. Gross yields are stronger at 10%–12% due to lower capital entry costs, though resale depth is shallower than DHA or Clifton.
Secondary and Emerging Corridors
Scheme 33 and Main University Road Extension: A rapidly developing corridor with growing bank branch presence. Entry prices are lower (PKR 1.8 crore to PKR 5 crore), and gross yields can reach 11%–13% — but vacancy risk post-lease expiry is meaningfully higher than prime corridors. Commercial listings in this area are tracked at Scheme 33 Karachi Commercial & Residential Listings.
North Nazimabad and Malir Cantt Commercial Strips: Mid-tier corridors with active bank branch presence from second-tier banks (Bank of Punjab, Silk Bank, Summit Bank). Yields are attractive at 11%–14% gross, but investor caution is warranted given rising commercial vacancy rates in North Nazimabad’s older plazas.
SITE Industrial Area: Primarily serves industrial banking clients. Standalone bank buildings here are occasionally available and offer strong yields, but the investor pool for resale is narrow.
Ground-Floor Unit vs. Standalone Branch Building
| Configuration | Typical Size | Indicative Asking Price | Gross Yield Range | Resale Depth |
|---|---|---|---|---|
| Ground-floor unit in commercial plaza (DHA Ph 5/6) | 800–1,800 sq ft | PKR 4.5–12 crore | 9%–11% | Strong (multiple buyers) |
| Ground-floor unit in commercial plaza (Clifton Blk 5) | 1,000–2,500 sq ft | PKR 6–22 crore | 8%–9.5% | Strong (premium address) |
| Ground-floor unit (Gulshan-e-Iqbal) | 600–1,500 sq ft | PKR 2.8–8 crore | 10%–12% | Moderate |
| Ground-floor unit (Scheme 33) | 500–1,200 sq ft | PKR 1.8–5 crore | 11%–13% | Shallow |
| Standalone bank branch building (any corridor) | 2,500–6,000 sq ft | PKR 12–45 crore | 7.5%–9% | Narrow (fewer buyers) |
Standalone branch buildings command higher absolute prices but compress yields due to the capital premium on full-building ownership. They also carry higher maintenance obligations and a narrower resale buyer pool. For most investors in the PKR 4 crore to PKR 15 crore range, a well-located ground-floor unit in DHA or Clifton offers the superior risk-adjusted return profile.
3. Understanding Bank Lease Structures Before You Buy
Typical Lease Tenure
Pakistani commercial banks operate on three primary lease formats:
- 3-year leases: Common for smaller branches, ATM-only kiosks, and secondary corridor locations. Lower security of income but more frequent rent reset opportunities.
- 5-year leases: The most common format for standard branch operations. Typically includes two 5-year renewal options, giving effective tenure of up to 15 years if the branch performs well.
- 10-year leases: Reserved for flagship branches, large-format banking halls, and purpose-built branch buildings. These command the highest capital premiums but provide the strongest income security.
Rent Escalation Clauses
Two escalation structures dominate bank leases in Pakistan:
Fixed Annual Increment (10% per annum): The most common structure. Rent increases by a fixed 10% each year regardless of inflation or market conditions. On a PKR 180,000/month starting rent, year-5 rent reaches approximately PKR 263,000/month — a 46% cumulative increase over the lease term.
CPI-Linked Escalation: Less common but increasingly negotiated by banks in longer leases. Escalation is tied to the Pakistan Bureau of Statistics CPI index. In high-inflation environments (Pakistan’s CPI averaged 20%–29% in 2023–2024), this structure can dramatically outperform fixed increments — but it also introduces income unpredictability for the landlord.
From an investor’s perspective, fixed 10% annual escalation is preferable for financial modeling. CPI-linked leases require more conservative underwriting.
The Lease Assignment Clause — The Single Most Critical Legal Point
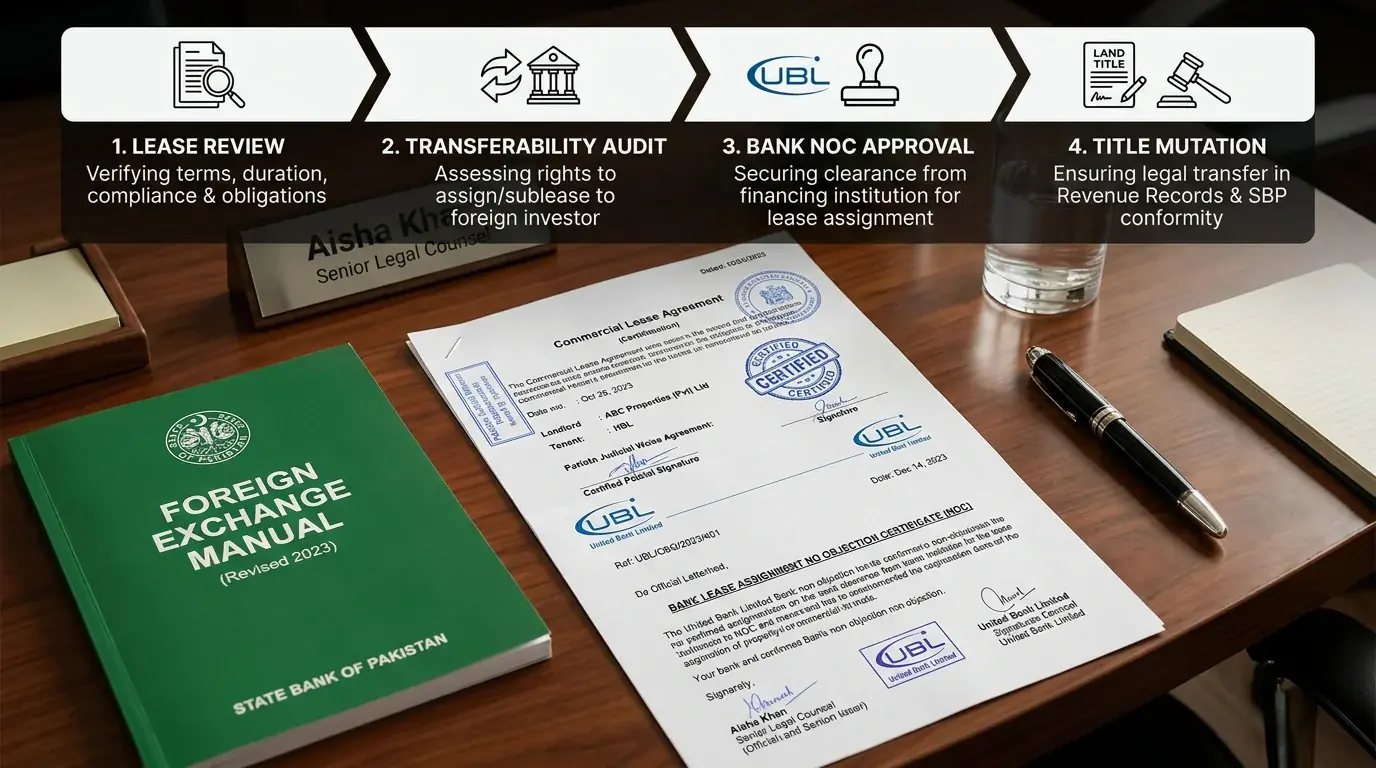
⚠️ Critical Advisory: Before signing any sale agreement for a bank-rented property, your lawyer must review the original lease agreement for a lease assignment clause. Many bank leases in Pakistan contain language stating that the lease is personal to the original landlord and cannot be transferred to a new owner without the bank’s prior written consent.
If this clause exists and the bank withholds consent — which can happen during branch rationalization reviews — you will have purchased a commercial property that is legally vacant from the bank’s perspective the moment the title transfers to your name. The bank can then negotiate a new lease on its own terms, or vacate entirely.
How to verify transferability before signing: 1. Obtain a certified copy of the original lease agreement from the seller. 2. Identify the assignment clause (typically in Clauses 15–22 of a standard commercial lease). 3. If the lease is non-transferable, require the seller to obtain the bank’s written No Objection Certificate (NOC) for lease assignment before you release any booking payment. 4. Confirm the NOC is on the bank’s official letterhead, signed by the Regional Manager or Head of Properties, and references the specific property address and lease number.
7-Point Lease Document Review Checklist
| # | Review Point | What to Verify |
|---|---|---|
| 1 | Lease commencement date | Confirm the exact start date and calculate remaining term |
| 2 | Monthly rent amount | Cross-check against bank’s rent payment records (last 12 months) |
| 3 | Annual escalation clause | Fixed % or CPI-linked; confirm current year’s applicable rent |
| 4 | Security deposit amount | Confirm amount held, who holds it, and transfer mechanism |
| 5 | Assignment / transferability clause | Non-transferable without bank consent? Obtain NOC before booking |
| 6 | Renewal options | How many renewal cycles? At what rent? Bank’s right to terminate? |
| 7 | Early termination penalty | What penalty does the bank pay if it vacates before lease expiry? |
4. How to Calculate Real Yield on a Bank-Rented Property in Karachi
Gross Yield vs. Net Yield — The Full Cost Stack
Gross yield is the number sellers advertise. Net yield is what you actually receive. The gap between the two on a commercial property in Karachi is significant and frequently misrepresented in informal market discussions.
Gross Yield Formula: (Annual Gross Rent ÷ Purchase Price) × 100
Net Yield Formula: ((Annual Gross Rent − Withholding Tax − Maintenance − Insurance) ÷ (Purchase Price + Acquisition Costs)) × 100
Withholding Tax on Commercial Rent Under FBR Section 155
Under FBR (Federal Board of Revenue) Section 155 of the Income Tax Ordinance 2001, any bank or corporate entity paying rent to a landlord is required to deduct withholding tax at source before remitting rent. The applicable rates for 2025–26 are:
- Active Tax Filer (Individual): 15% of gross rent deducted at source
- Non-Filer: 30% of gross rent deducted at source
This withholding tax is not a final tax — it is an advance against your annual income tax liability. If your total income tax liability is lower than the withheld amount, you can claim a refund through your annual return. However, for practical cash-flow modeling, investors should treat the 15% withholding as a direct yield reduction.
CVT, Stamp Duty, and Transfer Fee Impact on Acquisition Cost
At the point of purchase, the following costs compress your effective entry yield:
- Advance Tax on Purchase (Section 236K): 1.25% of FBR-declared value for active filers
- Stamp Duty (Sindh): 1%–2% of property value depending on sub-registrar schedule
- Capital Value Tax (CVT): 2% of FBR-declared value on commercial property transfers in Sindh
- Registration and Mutation Fees: PKR 50,000–PKR 150,000 depending on authority (KMC, Cantonment Board, or DHA)
- Legal and Advisory Fees: Typically 0.5%–1% of transaction value
Total acquisition cost overhead: 4.75%–6.25% above the agreed purchase price for an active tax filer.
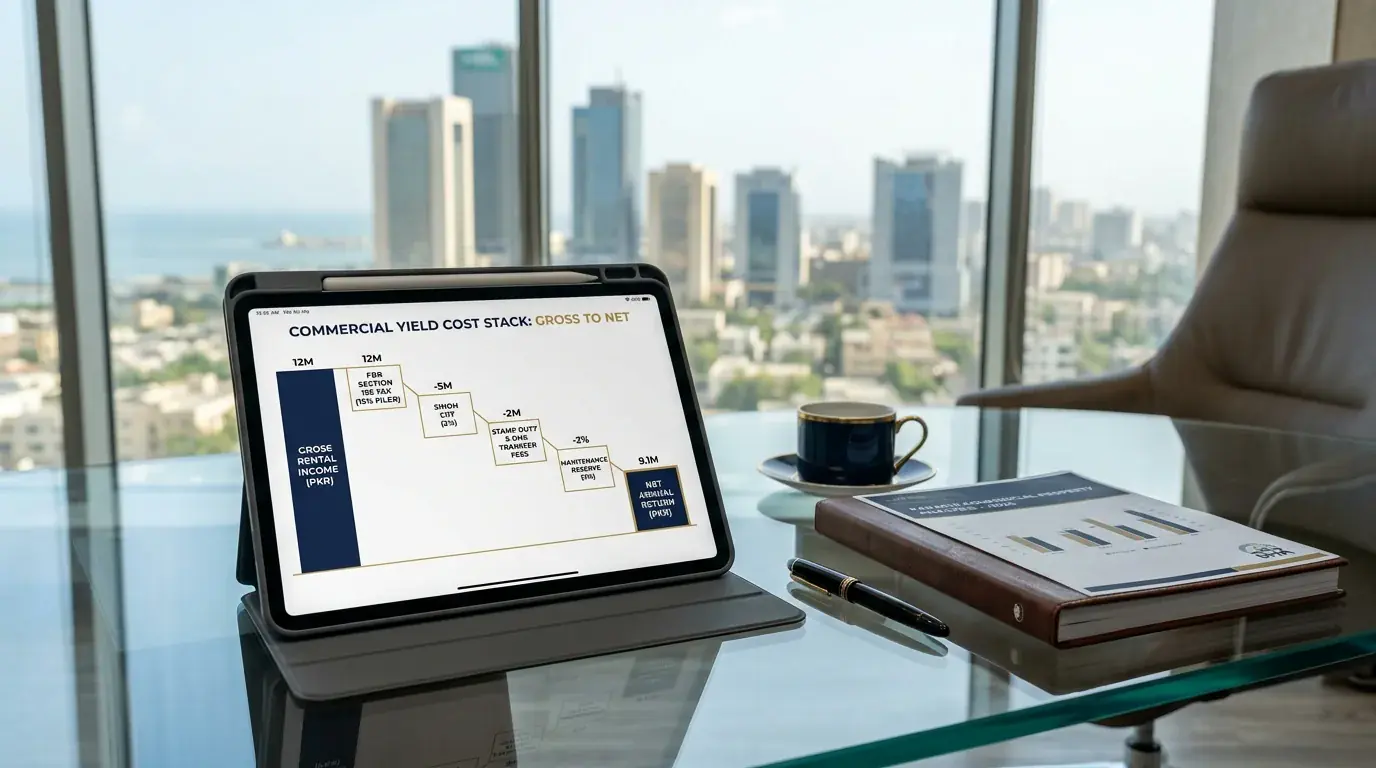
Worked Example: PKR 4.5 Crore Ground-Floor Unit in DHA Phase 6
| Line Item | Amount (PKR) | Notes |
|---|---|---|
| Purchase Price | 4,50,00,000 | Agreed market price |
| Advance Tax 236K (1.25%) | 5,62,500 | Active filer rate |
| CVT (2%) | 9,00,000 | Commercial property |
| Stamp Duty (1.5%) | 6,75,000 | Sindh average |
| Registration & Mutation | 1,00,000 | DHA transfer fees |
| Legal / Advisory (0.75%) | 3,37,500 | Estimated |
| Total Acquisition Cost | 4,75,75,000 | ~5.7% above purchase price |
| Monthly Gross Rent | 1,80,000 | Bank lease rate |
| Annual Gross Rent | 21,60,000 | |
| FBR Section 155 WHT (15%) | (3,24,000) | Deducted at source |
| Maintenance / Insurance | (1,20,000) | Estimated PKR 10,000/month |
| Net Annual Income | 17,16,000 | After WHT and costs |
| Gross Yield | 9.6% | On purchase price |
| Net Yield (on total acquisition cost) | 7.2% | After all costs |
| Break-Even Timeline | ~13.9 years | At current net income |
| Year-5 Net Income (10% escalation) | ~25,10,000 | Compounded escalation |
💡 Senior Property Advisor Insight (Muhammad Ali Dawood, MaxX Capitals): The break-even timeline improves materially when you factor in capital appreciation. DHA Phase 6 commercial units have appreciated at 8%–12% per annum over the past five years. A PKR 4.5 crore unit purchased today could realistically be worth PKR 7–8 crore in five years — meaning total return (income + capital) significantly outperforms the yield-only calculation. The net yield figure is your income floor, not your total return ceiling.
5. Valuation Methods Used for Bank-Rented Commercial Property
Income Capitalization Approach
The income capitalization method derives property value from the passing rent and a market capitalization rate. The formula is:
Property Value = Net Operating Income ÷ Capitalization Rate
For a DHA Phase 6 unit generating PKR 17,16,000 net annual income at a market cap rate of 8.5%: Implied Value = PKR 17,16,000 ÷ 0.085 = PKR 2,01,88,235
Wait — this appears lower than the PKR 4.5 crore asking price. This is intentional: the market cap rate for bank-rented properties in prime Karachi corridors is currently 6.5%–8%, not 8.5%, because buyers accept yield compression for institutional tenant security. Recalculating at 7%: PKR 17,16,000 ÷ 0.07 = PKR 2,45,14,285 — still below asking price, which reflects the capital appreciation premium embedded in DHA commercial pricing.
Comparable Sales Approach
Benchmarking against recent transactions in the same corridor is the most reliable ground-truth check. In DHA Phase 6 Badar Commercial, verified transactions in 2025–2026 show bank-rented ground-floor units (1,000–1,500 sq ft) trading at PKR 28,000–PKR 35,000 per sq ft. A 1,400 sq ft unit at PKR 32,000/sq ft = PKR 4.48 crore — consistent with the PKR 4.5 crore example above.
Replacement Cost Consideration for Standalone Buildings
For standalone bank branch buildings, the replacement cost method adds a floor to valuation: land value + construction cost at PKR 4,500–PKR 6,500 per sq ft for commercial-grade construction. A 3,500 sq ft standalone building on a 400 sq yd plot in DHA Phase 5: land (PKR 8 crore) + construction (PKR 2.1 crore) = PKR 10.1 crore replacement cost. If the asking price is PKR 12 crore with a bank lease, the PKR 1.9 crore premium represents the lease value — a reasonable premium for a 7-year remaining lease.
FBR-Declared Value vs. Market Value Divergence
| Valuation Basis | Clifton Block 5 Unit (1,200 sq ft) | DHA Phase 6 Unit (1,400 sq ft) |
|---|---|---|
| Income Capitalization (7% cap rate) | PKR 5.8–7.2 crore | PKR 4.2–5.1 crore |
| Comparable Sales (market rate/sq ft) | PKR 7.2–9.6 crore | PKR 3.9–4.9 crore |
| FBR SRO Declared Value | PKR 3.5–5.0 crore | PKR 2.2–3.1 crore |
| Actual Market Transaction Price | PKR 7–10 crore | PKR 4.5–6 crore |
The FBR SRO valuation consistently sits 30%–50% below actual market transaction prices in prime Karachi corridors. This divergence means your tax obligations at transfer (236K, CVT, stamp duty) are calculated on a lower base than your actual purchase price — a tax efficiency benefit for buyers. However, at the point of sale, your Capital Gains Tax will be calculated on the difference between your FBR-declared purchase value and FBR-declared sale value, which may not fully capture your actual capital gain.
6. Due Diligence Checklist for Buying a Bank-Rented Property in Karachi
Title Verification
Title verification for commercial property in Karachi must be conducted at the relevant authority — DHA Property Division for DHA-located units, the relevant Cantonment Board for cantonment-area properties, or KMC/Sindh Revenue Board for KDA-scheme properties. Verify the following through Sindh Zameen (sindhzameen.gos.pk) and the relevant authority’s records office:
- Ownership chain going back at least two transfers
- Any encumbrances, mortgages, or court orders registered against the property
- Mutation status — confirm the last mutation is in the seller’s name
- No pending litigation or attachment orders
Lease Document Audit
Beyond the 7-point checklist in Section 3, confirm: – The original lease is registered (not just a private agreement) – Rent amount matches the bank’s actual payment records – Security deposit is documented and the transfer mechanism is agreed in the sale agreement – Assignment NOC from the bank is in hand before any payment is released
Physical Inspection
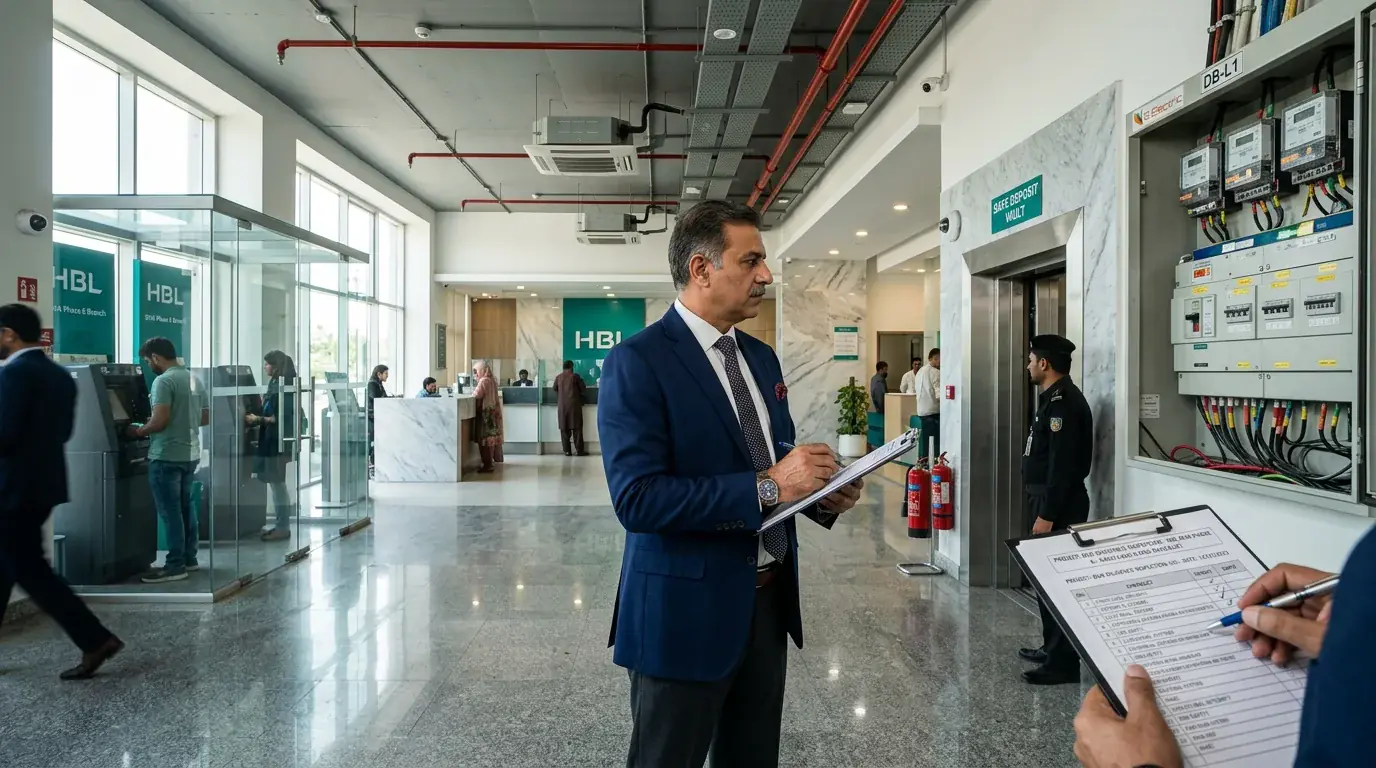
A physical inspection of a bank-rented commercial unit should cover: – Structural condition of the building (cracks, water seepage, foundation issues) – Utility connections: K-Electric meter in the owner’s name, SSGC connection status, water supply source – Fire safety compliance: extinguishers, emergency exits, sprinkler systems (required for bank branches) – Signage rights: confirm the lease grants the bank exclusive signage rights and what happens to signage at lease expiry – Parking allocation: how many dedicated parking spaces are assigned to the unit?
Bank Branch Rationalization Risk Assessment
Pakistan’s banking sector is actively rationalizing its physical branch network in response to digital banking adoption. Before purchasing, assess: – Is the branch a full-service branch or primarily an ATM/CDM kiosk? – What is the branch’s transaction volume and customer footfall? (Ask the bank’s regional manager informally.) – Has the bank opened a competing branch within 500 meters in the past 24 months? – Is the bank’s overall branch count in Karachi growing, stable, or declining?
20-Point Due Diligence Checklist
| # | Due Diligence Item | Verification Source |
|---|---|---|
| 1 | Title deed in seller’s name | DHA / KMC / Cantonment Board records |
| 2 | Ownership chain (last 2 transfers) | Sub-registrar / authority records |
| 3 | No encumbrances or mortgage | Authority records + seller affidavit |
| 4 | No court attachment or litigation | High Court / District Court search |
| 5 | Mutation completed in seller’s name | Revenue / authority mutation register |
| 6 | Building plan approval | SBCA / DHA Engineering |
| 7 | Commercial use NOC / conversion | SBCA / relevant authority |
| 8 | Original lease agreement (certified copy) | Seller disclosure |
| 9 | Lease registration confirmation | Sub-registrar stamp on lease |
| 10 | Remaining lease term calculation | Lease commencement + tenure |
| 11 | Current monthly rent (verified) | Bank payment records (last 12 months) |
| 12 | Annual escalation clause confirmed | Lease document review |
| 13 | Security deposit amount and holder | Lease document + seller confirmation |
| 14 | Assignment / transferability clause | Lease document — legal review |
| 15 | Bank NOC for lease assignment | Bank’s Regional Manager / Properties Dept |
| 16 | Utility connections (K-Electric, SSGC) | Utility bills in owner’s name |
| 17 | Structural inspection (no major defects) | Independent structural engineer |
| 18 | Fire safety compliance | Branch inspection |
| 19 | Parking allocation documented | Building plan + lease schedule |
| 20 | Branch rationalization risk assessment | Bank’s public branch network data |
7. Tax and Regulatory Framework for Commercial Property Transactions in Karachi
Capital Gains Tax (CGT) on Commercial Property
Under the Finance Act 2024–25, Capital Gains Tax on immovable property in Pakistan is charged at a flat rate of 15% on net realized capital profit for active tax filers, regardless of holding period. The previous tiered structure (where gains were exempt after 4–6 years of holding) has been abolished. This is a significant change that materially affects exit planning for commercial property investors.
For non-filers, CGT exposure is substantially higher and subject to FBR audit risk. Maintaining active filer status is non-negotiable for commercial property investors.
Withholding Tax at the Point of Sale — Sections 236C and 236K
| Tax | FBR Section | Rate (Active Filer) | Rate (Non-Filer) | Who Pays |
|---|---|---|---|---|
| Advance Tax on Purchase | 236K | 1.25% of FBR value | 3.75%–5% | Buyer |
| Advance Tax on Sale | 236C | 2.75% of FBR value | 5.5%–7.5% | Seller |
| Capital Gains Tax | CGT provisions | 15% of net profit | Higher rates + audit risk | Seller |
| Withholding Tax on Rent | 155 | 15% of gross rent | 30% of gross rent | Deducted by bank (tenant) |
| CVT (Commercial) | Sindh CVT Act | 2% of FBR value | 2% of FBR value | Buyer |
| Stamp Duty | Sindh Stamp Act | 1%–2% of value | 1%–2% of value | Buyer |
For the most current FBR valuation schedules and SRO notifications, refer to the official FBR Property Valuation portal (fbr.gov.pk).
Income Tax Treatment of Rental Income
For individual property owners, rental income from commercial property is taxed as income from property under Section 15 of the Income Tax Ordinance. After the 15% Section 155 withholding deduction at source, the net tax liability depends on your total income slab. For investors in the PKR 6 lakh+ annual income bracket, the marginal rate on rental income can reach 25%–35% — making the Section 155 withholding a partial advance, not a final settlement.
For corporate property owners (a private limited company owning the property), rental income is taxed at the corporate rate of 29%, but the company can offset legitimate business expenses against rental income, potentially reducing effective tax rates.
8. Negotiating the Right Price and Structuring the Deal
How Remaining Lease Term Affects Negotiating Leverage
The remaining lease term is your single most powerful negotiating variable:
- 6–18 months remaining: You hold significant leverage. The seller faces imminent vacancy risk. Negotiate a 10%–15% discount from asking price, or require the seller to obtain a confirmed lease renewal before closing.
- 2–4 years remaining: Balanced negotiation. The income stream is secure for the medium term, but you carry renewal risk. Price should reflect a modest discount to a fully-secured 7–10 year lease.
- 5+ years remaining: Seller holds leverage. The income security commands a premium. Focus negotiation on the security deposit transfer and assignment NOC rather than price.
Factoring in the Security Deposit
Bank leases typically carry security deposits of 3–6 months’ rent. On a PKR 180,000/month lease, this is PKR 540,000–PKR 1,080,000 held by the current owner. At transfer, this deposit must either be: – Transferred to the new owner (the bank issues a new deposit receipt in the buyer’s name), or – Deducted from the purchase price (the seller retains the deposit and the buyer receives a price reduction)
Failure to document the security deposit transfer in the sale agreement is one of the most common and costly oversights in commercial property transactions.
Payment Structures for Commercial Property Purchases
- Full cash purchase: Most common for bank-rented properties. Sellers of income-generating assets rarely accept installment arrangements.
- Partial bank finance: Available through commercial banks for up to 50%–60% of FBR-declared value. Note that bank finance on a property already occupied by a competing bank can create complications — the occupying bank may have a right of first refusal clause in its lease.
- Seller-financed arrangements: Rare but occasionally available when the seller is a corporate entity or developer. Typically structured as 70% upfront + 30% deferred over 12–24 months.
💡 Top 3 Negotiation Mistakes Buyers Make on Bank-Rented Properties
Mistake 1: Paying booking money before receiving the lease assignment NOC. Never release any payment — not even a token amount — until the bank’s written consent to assign the lease to your name is in hand. Without this, you have no enforceable right to the rental income.
Mistake 2: Accepting the seller’s gross yield calculation without modeling net yield. A seller quoting “10% yield” on a PKR 4.5 crore property at PKR 180,000/month is presenting gross yield. After Section 155 withholding, maintenance, and acquisition cost amortization, your net yield is closer to 7%–7.5%. Model it yourself before negotiating.
Mistake 3: Ignoring the lease expiry date in relation to your exit timeline. If you plan to sell in 3 years and the lease expires in 2 years, you may be selling a vacant commercial property — a fundamentally different (and lower-value) asset than a bank-rented one.
9. Risk Factors Every Investor Must Acknowledge Before Buying
Lease Non-Renewal Risk
When a bank’s lease expires, it has no obligation to renew. If the branch’s transaction volumes have declined, if the bank has opened a competing branch nearby, or if the branch is being converted to a digital-only service point, the bank will vacate. A vacant commercial unit in a secondary corridor can sit empty for 6–18 months before a replacement tenant is secured — at a lower rent than the departing bank paid.
Bank Branch Rationalization and Digital Banking Trends
Pakistan’s banking sector is undergoing structural transformation. Mobile banking users in Pakistan exceeded 15 million in 2024, and the State Bank of Pakistan’s Raast payment system is accelerating the shift away from branch-based transactions. HBL, MCB, and UBL have all publicly disclosed branch optimization programs. This does not mean bank branches are disappearing — but it does mean that branches in secondary corridors with declining footfall are at higher non-renewal risk than flagship branches in prime commercial districts.
Corridor-Specific Oversupply
Commercial vacancy rates in Scheme 33 and parts of North Nazimabad have risen in 2025–2026 as new commercial plazas have been completed faster than tenant demand has grown. Investors targeting these corridors for bank-rented properties should verify that the specific bank branch has renewed its lease at least once already — demonstrating the branch’s commercial viability at that location.
Risk Matrix
| Risk Factor | Probability (2026) | Financial Impact | Mitigation |
|---|---|---|---|
| Lease non-renewal at expiry | Medium (20%–35%) | High (6–18 months vacancy) | Buy with 5+ years remaining; verify branch performance |
| Lease non-transferability | Medium (30%–40%) | Critical (loss of tenant at transfer) | Obtain assignment NOC before any payment |
| Bank branch rationalization | Low-Medium (15%–25%) | High (permanent vacancy) | Avoid secondary corridors; focus on DHA/Clifton |
| Corridor oversupply (Scheme 33, N. Nazimabad) | Medium-High (35%–50%) | Moderate (lower replacement rent) | Stick to prime corridors for first acquisition |
| FBR tax rate changes | Low-Medium | Moderate (yield compression) | Maintain active filer status; model conservatively |
| Commercial property resale delay | Medium (30%–45%) | Moderate (capital tied up 6–18 months) | Price correctly at acquisition; avoid overpaying |
10. Is a Bank-Rented Property the Right Investment for You in 2026?
Investor Profile Fit
Bank-rented commercial property for sale in Karachi is best suited to investors who match the following profile:
- Capital size: PKR 4 crore to PKR 20 crore in deployable capital (not leveraged debt)
- Income tax bracket: Active filer with existing income — the Section 155 withholding is most efficiently utilized by investors who can offset it against their annual tax liability
- Time horizon: 5–10 years minimum; this is not a short-term trade
- Income priority: Investors who prioritize regular, predictable income over maximum capital appreciation
- Risk tolerance: Moderate — comfortable with lease renewal uncertainty but unwilling to accept tenant default risk
Comparing Bank-Rented Commercial Property Against Alternatives
| Investment Type | Entry Cost (PKR) | Gross Yield | Net Yield | Capital Appreciation | Resale Timeline | Risk Level |
|---|---|---|---|---|---|---|
| Bank-rented commercial (DHA/Clifton) | 4.5–15 crore | 9%–11% | 7%–9% | 8%–12% p.a. | 6–18 months | Moderate |
| Off-plan residential (DHA/Emaar) | 1.5–8 crore | 0% (pre-delivery) | 0% (pre-delivery) | 15%–25% (projected) | At delivery | Moderate-High |
| DHA commercial plot (holding) | 3–12 crore | 0% | 0% | 10%–18% p.a. | 3–12 months | Low-Moderate |
| Standard commercial unit (no bank tenant) | 2–10 crore | 10%–14% | 7%–10% | 6%–10% p.a. | 3–12 months | Moderate-High |
For investors who have already built capital appreciation exposure through off-plan residential or DHA plot holdings, adding a bank-rented commercial property provides genuine income diversification — a regular PKR income stream that is not correlated with construction delivery timelines or plot market cycles.
How MaxX Capitals Sources and Screens Verified Bank-Rented Inventory
MaxX Capitals maintains direct relationships with commercial property owners across DHA Phases 4, 5, 6, and 8, Clifton Block 5 and Block 9, and Gulshan-e-Iqbal. Our commercial advisory process for bank-rented properties includes:
- Lease document verification — we review the original lease before presenting any property to a buyer
- Assignment clause confirmation — we confirm transferability status before any client engagement
- Yield modeling — we provide a complete gross-to-net yield analysis for every property, not just the seller’s gross figure
- Title chain review — we verify ownership records at the relevant authority before recommending any acquisition
- Bank branch health assessment — we conduct informal assessments of branch footfall and renewal likelihood
Our verified commercial inventory is accessible through Properties for Sale in Karachi — Verified Inventory. For off-market bank-rented listings not published on the website, direct consultation is the most effective route.
Conclusion: Making a Disciplined Decision on Bank-Rented Property in Karachi
Bank rented property for sale in Karachi represents one of the most defensible income-generating asset classes available to Pakistani investors in 2026 — but only when acquired with full legal, financial, and physical due diligence. The institutional tenant advantage is real: banks pay on time, maintain their own interiors, and sign multi-year leases with contractual escalation. The 8%–10% net yield range is genuinely achievable in prime corridors.
What this guide has demonstrated, however, is that the gap between a well-structured acquisition and a poorly executed one is enormous. The lease assignment clause alone can transform a PKR 4.5 crore income-generating asset into a vacant commercial unit overnight. The Section 155 withholding tax compresses your cash flow by 15% from day one. And the FBR’s flat 15% CGT on all capital gains means your exit strategy must be modeled carefully, not assumed.
The investors who consistently generate strong returns from bank-rented commercial properties in Karachi are those who verify before they commit, model net yield rather than gross yield, and work with advisors who have direct experience negotiating lease assignments and reviewing commercial title chains — not those who act on a seller’s brochure and a verbal yield estimate.
For investors with PKR 4 crore to PKR 20 crore in deployable capital, active tax filer status, and a 5–10 year income horizon, this asset class deserves serious consideration as part of a diversified Karachi property portfolio.
Ready to Navigate Your Next Property Decision?
Before committing booking money or signing any commercial sale agreement, ensure your lease assignment, title chain, and yield calculations are independently verified.
Consult with MaxX Capitals: – 📞 Direct Advisory: 0333-2110529 | 0300-0801881 – 💬 WhatsApp: Connect on WhatsApp (0333-2110529) – 🌐 Online Consultation: Book a Confidential Appointment – 📍 Headquarters: SF-32, Vincy Mall, Block 9, Clifton, Karachi, Sindh, Pakistan
Join The Discussion