
 by
When the Capital Development Authority announced plans to commercialize its 16-kilometre G.T. Road land holding — acquired in 1967 and left largely dormant for nearly six decades — the question that immediately surfaced in every serious investor conversation was the same: what are the actual CDA commercial plot rates per square yard, and do the numbers justify capital allocation at this stage?
The answer requires more than repeating the PKR 7.5 Lac headline figure. It demands a structured audit of how that benchmark was derived, what the realistic revenue ceiling looks like across 1.21 million square yards of net developable land, and how this corridor stacks up against established CDA commercial benchmarks in Blue Area, G-9 Markaz, and I-8 Markaz — where verified auction data already exists. This article builds that model from the ground up, using confirmed CDA auction records, official FAR regulations, and on-ground rate intelligence from the western Islamabad belt.
For a verified breakdown of the spatial boundaries, 2,000-kanal land configuration, and anti-fraud guidance on unauthorized file marketing, read our verified master plan and spatial boundary breakdown of the CDA G.T. Road corridor.
Key Takeaways (Executive Summary)
Primary Insight: PKR 7.5 Lac per sq yd is a CDA feasibility model benchmark — not a confirmed reserve price. Final auction rates will be set closer to the first tranche launch, and could range from PKR 7.5 Lac to PKR 1.1 Million per sq yd depending on plot size, frontage, and corridor position.
Financial Impact: At PKR 7.5 Lac/sq yd across ~1.21 million sq yds, gross theoretical yield reaches PKR 907.5 Billion — well above the conservative PKR 500 Billion baseline. A phased auction structure protects market absorption.
Legal / Due Diligence Check: No authorized bookings, files, or pre-launch registrations exist as of 2026. All inventory will be disposed of exclusively through official CDA public auctions at the Jinnah Convention Centre or designated CDA online portals.
Actionable Recommendation: Corporate developers and logistics operators with long-horizon capital (5–10 years) should begin auction readiness preparation now. Retail investors seeking near-term rental yield should wait for the first tranche results before committing.
Table of Contents
1. Understanding the PKR 7.5 Lac Per Sq Yd Starting Benchmark
Before any capital allocation decision can be made, investors need to understand precisely what the PKR 7.5 Lac figure represents — and what it does not.
What ‘Feasibility Model Reserve Price’ Means vs. a Confirmed Auction Floor
A feasibility model reserve price is an internal CDA planning estimate used to determine whether a project is financially viable before formal auction design begins. It is derived by the CDA’s Planning and Finance wings to test whether projected auction revenues will cover land acquisition costs, infrastructure outlays, and administrative overheads — with a surplus that justifies the project.
This is categorically different from a confirmed reserve price, which is the legally binding minimum bid floor published in the official auction notice (typically 30–45 days before the auction date at the Jinnah Convention Centre). The confirmed reserve price can be higher or lower than the feasibility benchmark depending on market conditions at the time of launch, the specific plot’s frontage and depth, and the competitive demand environment among registered bidders.
The practical implication: investors who treat PKR 7.5 Lac/sq yd as a guaranteed entry price are making a planning error. The confirmed reserve price for premium frontage plots — particularly those at major intersections along the 16km strip — could open materially higher.
How CDA Derives Starting Benchmarks — Land Acquisition Cost, Infrastructure Outlay, and Market Comparables
CDA’s benchmark derivation methodology follows a three-input model:
Historical Land Acquisition Cost: The G.T. Road strip was acquired in 1967 under the CDA Ordinance. While the original acquisition cost is negligible in today’s terms, CDA’s finance wing applies a current replacement value methodology — essentially, what it would cost to acquire equivalent highway-frontage land today in the ICT belt. This anchors the floor.
Infrastructure Outlay: The 16km strip requires dual service roads, multi-tier utility ducts, demarcation pillars, drainage infrastructure, and partial funding toward the Tarnol flyover/underpass interchange (a PKR 2 Billion PC-I already tabled). These costs are amortized across the net developable area to arrive at a per-sq-yd infrastructure loading.
Market Comparables: CDA benchmarks against its own most recent auction outcomes. The New Blue Area (G-9/F-9) auctions, which yielded PKR 16 Billion to PKR 17 Billion per Jinnah Convention Centre session, provide the upper-end reference. I&T Centre rates provide the lower-end anchor. The G.T. Road strip is positioned between these poles.
The Range: PKR 7.5 Lac to PKR 1.1 Million Per Sq Yd and What Drives the Spread
The PKR 7.5 Lac to PKR 1.1 Million range is not arbitrary. Four variables drive where a specific plot lands within this band:
- Intersection Proximity: Plots adjacent to the Tarnol Phatak interchange, the Sangjani junction, or the EME College entry node command a premium of 20%–35% above mid-strip plots.
- Plot Depth and Frontage: Larger plots (2,000–4,000 sq yd) with 100-foot-plus frontage on the national highway attract institutional bidders and carry higher per-sq-yd premiums due to FAR leverage.
- Auction Tranche Sequence: First-tranche plots — typically the most strategically located — historically attract the highest bid premiums. Later tranches in less prominent positions tend to clear closer to reserve.
- Utility Readiness: Plots with confirmed IESCO grid proximity and SSGC gas line access at the time of auction will attract higher bids than those requiring buyer-funded utility extensions.
2. The Rs 500 Billion to Rs 975 Billion Revenue Model — How the Numbers Work
Gross Land Area: 1,210,000 Sq Yds Across ~2,000 Net Kanals
The CDA’s gross land holding along the G.T. Road strip is 3,550 Kanals, acquired as a 200-foot-wide linear corridor flanking both sides of N-5 from the EME College vicinity to the Nicholson Monument. After carving out 100-foot rights-of-way, dual service lanes, utility ducts, green buffers, and civic infrastructure reserves, the net developable commercial area is approximately 2,000 Kanals — equivalent to roughly 1,210,000 square yards.
This is the base figure against which all revenue projections are modeled.
Revenue Sensitivity Table: PKR 500B at Conservative Rate vs. PKR 975B at Upper-Range Rate
The following sensitivity model shows gross theoretical revenue at three rate scenarios across the 1.21 million sq yd net area. Note that these are gross land sale revenues — they do not account for infrastructure expenditure, legal costs, or phased absorption discounts.
| Rate Scenario | Rate Per Sq Yd (PKR) | Net Area (Sq Yds) | Gross Theoretical Revenue | Scenario Classification |
|---|---|---|---|---|
| Conservative | PKR 7,50,000 | 1,210,000 | PKR 907.5 Billion | Feasibility model floor; all plots at minimum benchmark |
| Mid-Range | PKR 9,00,000 | 1,210,000 | PKR 1,089 Billion | Realistic if first two tranches clear above reserve |
| Upper Range | PKR 11,00,000 | 1,210,000 | PKR 1,331 Billion | Achievable if premium intersection plots attract competitive bidding |
| CDA Published Baseline | PKR 7,50,000 (blended) | ~667,000 (partial) | PKR 500 Billion | Conservative partial-area model cited in official communications |
Important clarification on the PKR 500 Billion figure: CDA’s official communications reference PKR 500 Billion as a conservative baseline, likely modeled on a partial area absorption scenario (approximately 55%–60% of net developable land at the floor rate), not on full area disposal at PKR 7.5 Lac/sq yd. The full-area model at the floor rate already yields PKR 907.5 Billion — which is why the upper-end projection of PKR 975 Billion+ is entirely credible.
Why CDA’s Phased Auction Structure Protects Market Absorption and Prevents Rate Collapse
CDA will not release all 2,000 Kanals in a single auction. The phased structure — modeled on the successful New Blue Area (G-9/F-9) methodology — releases inventory in 3 to 5 tranches over multiple years. This approach serves three functions:
- Price Discovery: Early tranches establish market-clearing rates. If first-tranche plots clear at PKR 9 Lac/sq yd, subsequent tranches can be priced accordingly — preventing the rate collapse that would occur if 1.21 million sq yds hit the market simultaneously.
- Capital Absorption: Institutional buyers need 12–24 months between major capital commitments. Phased releases allow the same pool of bidders to participate across multiple tranches.
- Infrastructure Sequencing: Utility provisioning, service road construction, and encroachment clearance can be completed in phases rather than requiring full-strip readiness before any auction proceeds.
3. Five-Corridor Rate Comparison: CDA Blue Area vs GT Road Commercial and Established Benchmarks
This is the comparison that institutional buyers need most — a verified, apples-to-apples matrix of CDA commercial plot rates per square yard across all active corridors, with realized auction data rather than asking prices.
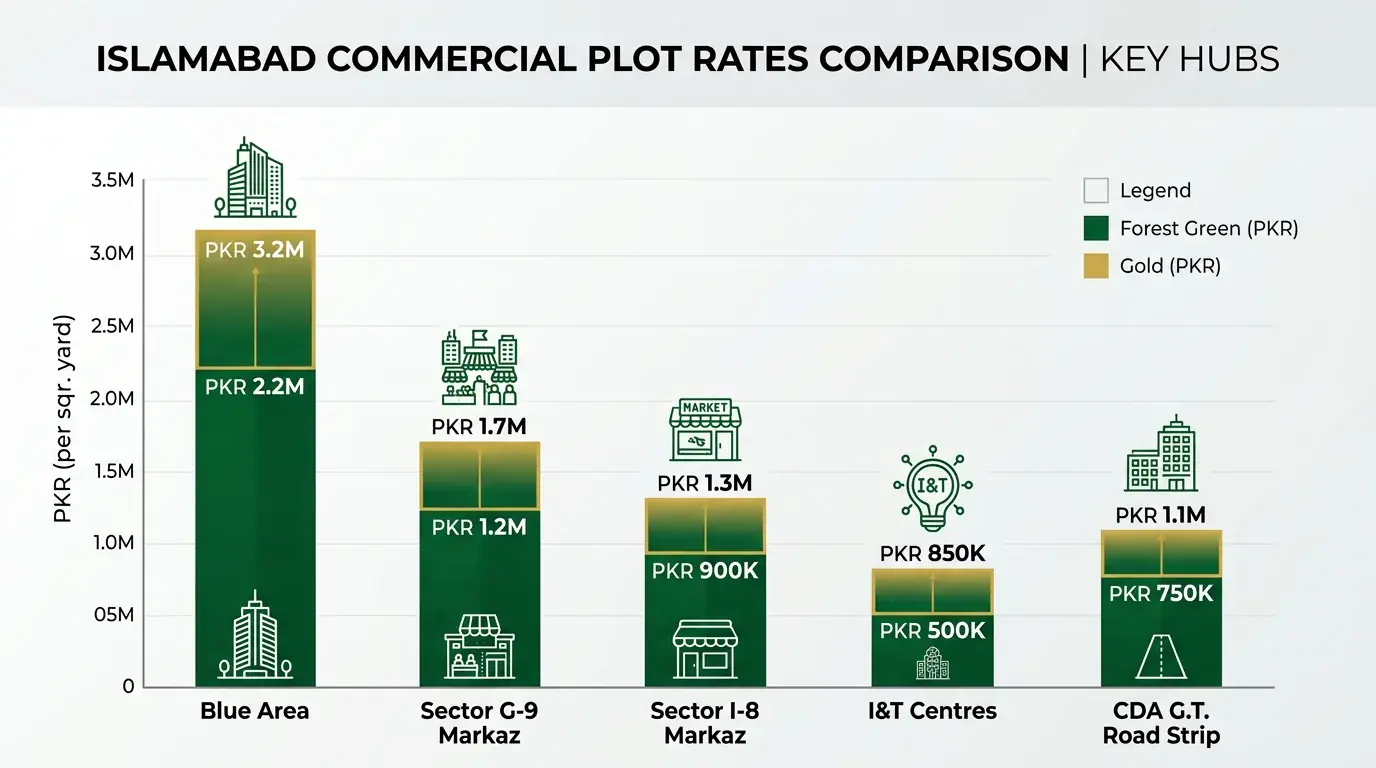
Blue Area (F-9/G-9) — PKR 2.2M to PKR 3.2M Per Sq Yd and the High-FAR Corporate HQ Premium
Blue Area commands Islamabad’s highest commercial land rates for a structural reason: it is the only CDA-designated Central Business District with confirmed FAR ratios of 1:8 to 1:10+, uncapped building heights along designated commercial avenues, and a 30-year track record of corporate bank headquarters, multinational offices, and government-adjacent institutional tenants. The PKR 2.2M–3.2M/sq yd range reflects not just land value but the embedded development rights — a 3,500 sq yd plot at PKR 3M/sq yd carries PKR 10.5 Billion in land cost but enables a 35,000 sq yd GLA tower that can generate PKR 800M–PKR 1.2B in annual rental income at PKR 200–350/sq ft/month.
G-9 Markaz and I-8 Markaz — PKR 900K to PKR 1.7M and the Retail Footfall Multiplier
G-9 Markaz (Karachi Company area) and I-8 Markaz represent Islamabad’s highest-footfall retail commercial nodes outside Blue Area. Their PKR 900K–PKR 1.7M/sq yd range reflects the retail footfall multiplier — these are fully inhabited, high-density residential sectors with captive consumer bases. Commercial plots here are smaller (300–1,000 sq yd) but generate immediate rental income from ground-floor retail, making them attractive to yield-focused buyers rather than development-scale investors.
I&T Centres (G-6, I-9, I-10) — PKR 500K to PKR 850K and the Industrial Logistics Baseline
Industrial and Trade Centres represent CDA’s lowest commercial rate tier, reflecting their industrial-logistics use profile (spare parts, workshops, warehousing) rather than premium retail or corporate office. Their PKR 500K–PKR 850K/sq yd range establishes the structural floor for CDA commercial land — and is the reference point that makes the G.T. Road strip’s PKR 750K–PKR 1.1M benchmark appear credible rather than aspirational.
G.T. Road Strip at PKR 750K to PKR 1.1M — Entry Discount or Structural Discount?
wp:image {“id”:40814,”sizeSlug”:”full”,”linkDestination”:”none”}
/wp:image
The critical question for investors is whether the G.T. Road strip’s discount to Blue Area (65%–75%) reflects a genuine entry opportunity or a structural limitation that will persist. The honest answer is: both, depending on your investment horizon.
The five-corridor comparison matrix below provides the complete picture:
| Corridor | Rate Range (PKR/Sq Yd) | Typical Plot Size | Realized Auction Price Range | Primary Value Driver |
|---|---|---|---|---|
| Blue Area (F-9/G-9) | PKR 2,200,000 – PKR 3,200,000 | 1,333 – 3,500 sq yd | PKR 3.5B – PKR 9.1B | Central business district, high FAR, corporate HQ demand |
| G-9 Markaz | PKR 1,200,000 – PKR 1,700,000 | 400 – 1,000 sq yd | PKR 600M – PKR 1.5B | High-density retail footfall, captive residential catchment |
| I-8 Markaz | PKR 900,000 – PKR 1,300,000 | 300 – 800 sq yd | PKR 350M – PKR 850M | Islamabad Expressway access, Rawalpindi transit link |
| I&T Centres (G-6, I-9, I-10) | PKR 500,000 – PKR 850,000 | 200 – 500 sq yd | PKR 150M – PKR 400M | Industrial logistics, spare parts, secondary trade |
| G.T. Road Strip (Planned) | PKR 750,000 – PKR 1,100,000 | 500 – 2,500 sq yd | PKR 375M – PKR 2.5B (est.) | 16km transit frontage, CPEC logistics, highway retail |
For a broader view of how this corridor is already lifting property values across B-17, TopCity-1, and the Srinagar Highway belt, see how this corridor is already lifting property values across B-17, TopCity-1, and the Srinagar Highway belt.
4. FAR Ratios, Plot Sizes, and Development Yield Potential
Expected Plot Dimension Range — 500 Sq Yd to 4,000 Sq Yd and What Each Tier Attracts
CDA’s design committee, headed by Deputy Director General (Architecture) Ali Abdullah, is finalizing plot dimension standards across four tiers:
- 500–800 sq yd: Suited to petrol stations, fast-food drive-throughs, single-brand showrooms, and small logistics depots. These will attract owner-operators and small commercial developers.
- 800–1,500 sq yd: The sweet spot for mid-scale retail plazas, car dealerships, and branded service centres. Most competitive bidding is expected in this range.
- 1,500–2,500 sq yd: Hypermarket anchors, multi-brand automotive showroom complexes, and mixed-use retail-plus-office developments. Institutional and corporate balance-sheet buyers.
- 2,500–4,000 sq yd: Large-format logistics hubs, cold-chain warehousing, and potential hotel/hospitality developments given the airport proximity. Long-horizon developers only.
How FAR Ratios Determine Gross Leasable Area and Net Development Value
wp:image {“id”:40815,”sizeSlug”:”full”,”linkDestination”:”none”}
/wp:image
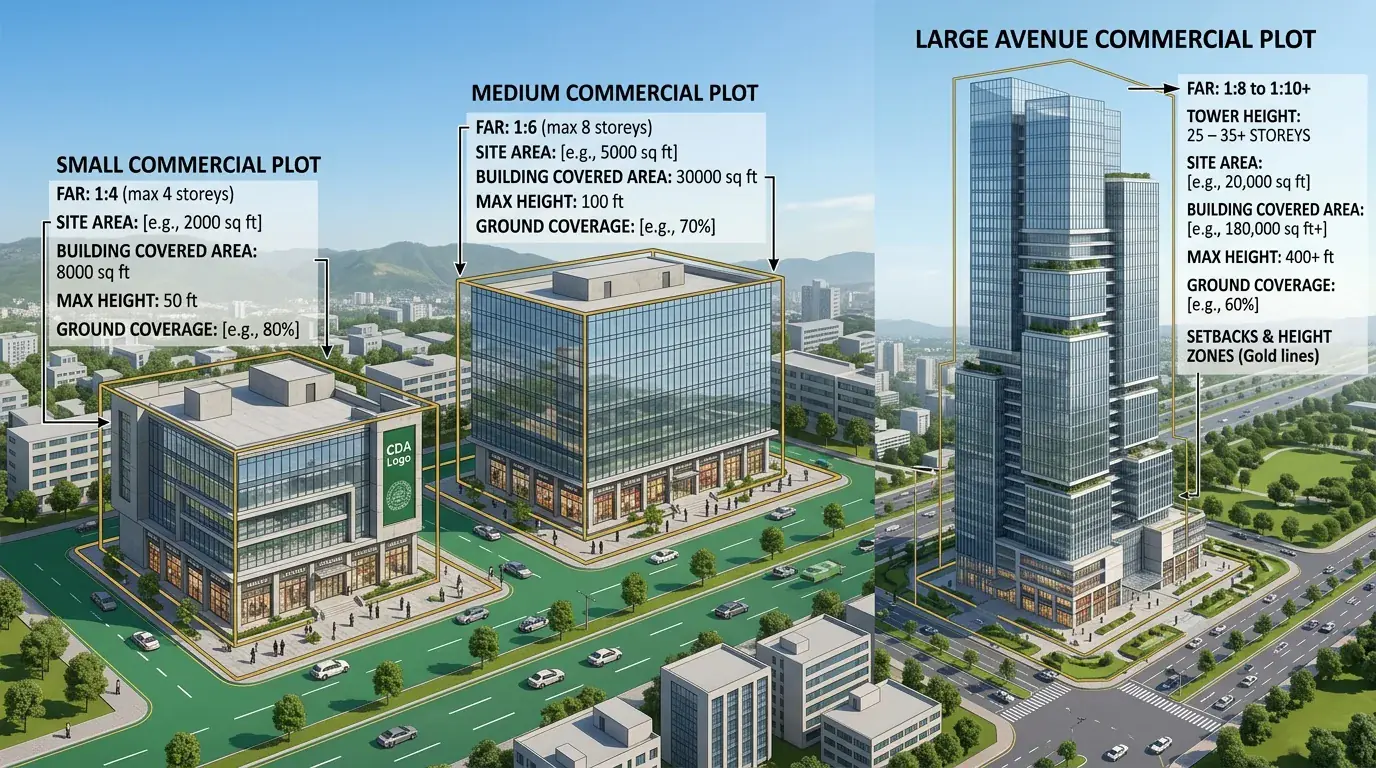
CDA’s Building Control Regulations apply FAR ratios dynamically based on plot size and highway frontage. For the G.T. Road strip — classified as a designated commercial avenue with 200-foot ROW — the applicable FAR framework is:
| Plot Size Category | Applicable FAR | Max Ground Coverage | Estimated GLA (at FAR 1:4) | Estimated GLA (at FAR 1:6) |
|---|---|---|---|---|
| Small (500–800 sq yd) | 1:4 to 1:5 | 70%–80% | 2,000 – 3,200 sq ft | 3,000 – 4,800 sq ft |
| Medium (800–1,500 sq yd) | 1:5 to 1:6 | 75%–80% | 4,000 – 7,500 sq ft | 6,000 – 11,250 sq ft |
| Large (1,500–2,500 sq yd) | 1:6 to 1:8 | 75%–80% | 9,000 – 20,000 sq ft | 13,500 – 30,000 sq ft |
| Highway Frontage (2,500–4,000 sq yd) | 1:8 to 1:10+ | Up to 80% | 20,000 – 40,000 sq ft | 30,000 – 60,000 sq ft |
GLA estimates are indicative based on CDA Building Control Regulations for designated commercial avenues. Actual permissible GLA is subject to final building plan approval.
Critically, CDA has eliminated rigid storey caps along designated commercial avenues. Building heights are now governed by allowable FAR, plot depth, and adjacent ROW — enabling mid-to-high-rise developments of 18 to 45+ storeys where soil conditions and FAR permit. This is the structural feature that makes large G.T. Road plots genuinely comparable to Blue Area in development potential, even if the current land rate differential remains significant.
Automotive Showrooms, Hypermarkets, Logistics Hubs, and Branded Retail — Which Use Cases Justify the Rate?
At PKR 7.5 Lac–PKR 1.1M/sq yd, the use cases that generate sufficient returns to justify the land cost are:
- Automotive Showrooms and Service Centres: The 120,000+ daily vehicle count on N-5 G.T. Road creates unrivaled visibility for automotive brands. A 1,000 sq yd showroom plot at PKR 9 Lac/sq yd (PKR 900M land cost) can generate PKR 8M–PKR 12M/month in rental income from a premium automotive tenant — a 10%–16% gross yield on land cost alone, before construction.
- Hypermarkets and Large-Format Retail: The residential catchment (B-17, D-17, Faisal Town, TopCity-1, Mumtaz City, C-15/C-16) represents over 500,000 residents within a 15-minute drive. A 2,500 sq yd hypermarket anchor plot justifies PKR 1M+/sq yd on footfall economics alone.
- Logistics and Cold-Chain Hubs: The 12–18 minute proximity to the New Islamabad International Airport cargo terminal, combined with CPEC transit route alignment, makes 3,000–4,000 sq yd plots viable for bonded warehousing and cold-chain logistics at rates that comfortably service PKR 1.1M/sq yd land cost.
- Branded Fuel and Convenience Retail: Highway-frontage fuel plazas with convenience retail and food courts are among the highest-yield commercial formats on national highways. These operators can absorb PKR 7.5 Lac–PKR 9 Lac/sq yd on 500–800 sq yd plots.
For verified commercial yield benchmarks from comparable Islamabad corridors, review our analysis of GoldCrest Commercial DHA 2 Islamabad.
5. CDA Auction Bidding Terms and Payment Milestone Structure
Understanding the CDA commercial plot auction 2026 payment structure is essential before registering as a bidder. The terms carry a fundamentally different risk profile from private developer installment plans.
The 5% USD Rebate Clause — What It Means for Overseas Pakistani Bidders
CDA offers a 5% discount on the winning bid amount for payments remitted in US Dollars (USD) through official banking channels. This is separate from — and stackable with — the advance payment rebate. For an overseas Pakistani bidder winning a plot at PKR 2 Billion, the USD remittance discount alone saves PKR 100 Million. Combined with the advance payment rebate (detailed below), the maximum combined discount reaches 10% off the winning bid amount.
The practical mechanics: the bidder must remit the full USD equivalent of the winning bid within 30 days of bid acceptance, through a designated State Bank of Pakistan-approved foreign currency account. The State Bank of Pakistan (SBP) remittance guidelines govern the eligible transfer channels.
25% Payment at Building Plan Submission — Timeline and Compliance Requirements
The standard CDA auction payment structure operates on a milestone basis:
- Initial 25% Deposit: Due within 30 days of bid acceptance at the Jinnah Convention Centre. This payment unlocks the right to submit building plans for CDA architectural approval — meaning the buyer can begin design and planning work before completing full payment.
- Building Plan Approval Phase: Once the 25% is paid, the buyer submits architectural drawings to CDA’s Building Control wing for review. This phase typically takes 60–120 days depending on plot size and design complexity.
The 25% milestone is strategically important: it gives institutional buyers a 60–120 day window between initial payment and possession to finalize financing, secure anchor tenants, and complete structural engineering — without the full capital being deployed.
75% Balance at Possession — Risk Exposure During the Construction and Demarcation Phase
Physical possession of the plot is handed over once the buyer reaches 75% cumulative payment of the winning bid amount. The remaining 25% (after the initial deposit) must be paid before possession is granted.
The risk window between 25% payment and possession is the most critical phase for buyers to monitor:
- Demarcation Delays: If encroachment clearance on adjacent plots is incomplete, CDA may delay physical demarcation and possession even after 75% payment is received.
- Litigation Stays: Hereditary claimants or encroachers with civil court stay orders can freeze demarcation on specific plot numbers. Buyers should request a litigation-clear certificate from CDA’s legal wing before making the 25% payment.
- Infrastructure Readiness: Possession of the plot does not guarantee immediate utility connections. IESCO grid capacity allocation and SSGC gas line extension timelines are separate processes.
Comparison with Private Developer Installment Plans: Why CDA Terms Carry Different Risk Profiles
| Parameter | CDA Auction Terms | Private Developer Installment Plans |
|---|---|---|
| Title Security | Direct CDA sovereign leasehold — highest security | Developer-issued allotment letter; title transfers on completion |
| Payment Structure | 25% at plan submission, 75% at possession | Typically 10%–20% booking + 36–60 month installments |
| Possession Timeline | Linked to 75% payment milestone | Linked to construction completion (often delayed) |
| Advance Payment Benefit | 5% rebate + 5% USD discount (10% max) | Varies; some developers offer 5%–8% cash discounts |
| Default Risk | CDA cancels allotment; partial refund per CDA policy | Developer may forfeit booking; legal recovery is complex |
| Regulatory Oversight | CDA (Capital Development Authority) directly | REAP/RERA oversight varies by province |
The fundamental difference: CDA auction terms require larger upfront capital but deliver sovereign-grade title security. Private developer plans offer lower entry capital but carry developer execution risk. For institutional buyers, CDA’s terms are structurally preferable despite the higher initial capital requirement.
You can review our full inventory of verified commercial plots for sale in Islamabad to compare CDA and private corridor options side by side.
6. Historical CDA Auction Yield Data — What Jinnah Convention Centre Sessions Tell Us
PKR 16B–17B Per Session: How CDA’s Recent Auction Rounds Performed
CDA’s Jinnah Convention Centre commercial auctions have consistently generated PKR 16 Billion to PKR 17 Billion per session in recent rounds — a figure that reflects both the depth of institutional demand for CDA-title commercial land and the competitive bidding dynamics that emerge when supply is deliberately constrained. These sessions typically feature 15–25 plots across multiple sectors, with registered bidders including corporate developers, overseas Pakistani investors, and institutional funds.
The PKR 16B–17B per-session yield is the most important data point for modeling G.T. Road tranche outcomes. If CDA releases 8–12 plots per tranche (consistent with recent session sizes), and those plots average 1,000–1,500 sq yd each at PKR 9 Lac–PKR 1.1M/sq yd, a single G.T. Road auction session could generate PKR 10B–PKR 20B — within the established range.
Bid Premium Patterns — How Much Above Reserve Price Do Winning Bids Typically Land?
Based on verified CDA auction records, winning bids for premium commercial plots consistently clear 15%–45% above the published reserve price. The premium is highest for:
- Corner plots with dual-frontage on intersecting roads
- Plots adjacent to established commercial anchors (petrol stations, banks, fast-food chains)
- First-tranche plots in newly launched corridors (where scarcity premium is highest)
For the G.T. Road strip, if the confirmed reserve price is set at PKR 7.5 Lac/sq yd, realistic clearing prices for premium plots could land at PKR 8.6 Lac–PKR 10.9 Lac/sq yd — which is why the PKR 7.5 Lac–PKR 1.1M range in the feasibility model is internally consistent.
What the New Blue Area (G-9/F-9) Auction Precedent Predicts for G.T. Road Tranche Pricing
The New Blue Area auctions in G-9/F-9 are the most instructive precedent. When CDA first launched those plots, reserve prices were set conservatively — and winning bids cleared 25%–40% above reserve in the first tranche. By the third tranche, reserve prices had been revised upward to reflect realized market rates, and bid premiums normalized to 10%–20% above the revised reserve.
The G.T. Road strip should follow a similar trajectory: first-tranche plots will likely clear significantly above the PKR 7.5 Lac floor, establishing a higher baseline for subsequent tranches. Investors who wait for later tranches to “see how the market responds” may find that the entry rate has already moved to PKR 9 Lac–PKR 1.1M/sq yd.
For a comprehensive view of commercial property opportunities across Islamabad, including projects already benefiting from the western corridor expansion, our Islamabad property hub provides verified current listings.
7. Honest Risk Disclosures: What the Revenue Model Does Not Guarantee
⚠️ Risk Disclosure Notice: The following section details material risks that every prospective bidder must evaluate before committing capital to CDA G.T. Road commercial plots. These risks are not hypothetical — they are documented challenges that have affected previous CDA commercial projects.
Feasibility Benchmarks Are Not Confirmed Reserve Prices — The Gap Risk
The PKR 7.5 Lac/sq yd figure is a CDA internal feasibility model benchmark. The confirmed reserve price will be published in the official auction notice, which CDA typically releases 30–45 days before the auction date. There is no legal or regulatory mechanism that prevents CDA from setting the confirmed reserve price higher than the feasibility benchmark if market conditions at the time of launch support a higher floor.
Conversely, if macroeconomic conditions deteriorate — PKR depreciation, interest rate increases, or a broader real estate market correction — CDA could delay the auction or revise the reserve price downward. Investors should not make capital commitments based on the PKR 7.5 Lac benchmark alone.
Litigation, Stay Orders, and Encroachment Clearance Delays That Could Defer Auction Timelines
The 16km strip has over 100 documented illegal structures — shops, warehouses, filling stations, marble factories, and encroached boundary walls — that have been served demolition notices. However, several encroachers and hereditary claimants have approached civil courts for compensation reassessment under the original 1967 acquisition. The Capital Development Authority legal wing is tasked with vacating these stays before plot demarcation can proceed.
Historical precedent from other CDA commercial projects suggests that litigation clearance can add 12–24 months to auction timelines. Investors should monitor CDA’s official communications and the Islamabad High Court cause list for stay order status before registering for auctions.
Infrastructure Deficit Risk: IESCO Grid Capacity and Water Supply Constraints on Commercial High-Rise Development
Commercial high-rise development on the G.T. Road strip will require substantial IESCO grid capacity allocation and water supply provisioning from the Sangjani water treatment complex. Neither of these utilities is currently sized for the commercial density that 2,000 Kanals of high-FAR development would generate.
CDA’s plan to earmark a portion of auction revenues for infrastructure investment is directionally correct — but the sequencing risk is real: plots may be auctioned and possession granted before utility infrastructure is ready for commercial high-rise construction loads. Buyers should factor in 12–24 months of utility provisioning time after possession before construction can begin at full FAR.
🔴 Risk Rating Summary
8. Is the G.T. Road Strip a Credible Alternative to Blue Area for Capital Allocation?
The Entry-Price Advantage: PKR 7.5 Lac vs. PKR 2.6M — A 3.5x Rate Differential
The 3.5x rate differential between the G.T. Road benchmark (PKR 7.5 Lac/sq yd) and Blue Area’s current rate (PKR 2.6M–PKR 3.2M/sq yd) is the most compelling headline figure for capital-constrained institutional buyers. A 1,500 sq yd plot on G.T. Road at PKR 9 Lac/sq yd costs PKR 1.35 Billion. An equivalent plot in Blue Area costs PKR 3.9 Billion–PKR 4.8 Billion. The G.T. Road buyer deploys PKR 2.5B–PKR 3.5B less capital for a comparable FAR-enabled development footprint.
The Trade-Off: Lower Entry Rate vs. Lower Immediate Footfall and Longer Value Maturation Timeline
The entry-price advantage comes with a structural trade-off that investors must price honestly:
- Footfall Maturation: Blue Area has 30+ years of corporate tenant demand, established banking infrastructure, and government-adjacent institutional occupancy. The G.T. Road strip is a greenfield commercial corridor — footfall will build over 5–10 years as the residential catchment matures and anchor tenants establish presence.
- Rental Yield Timeline: Investors expecting immediate rental income comparable to Blue Area will be disappointed. Realistic commercial rental yields on G.T. Road will likely be 4%–7% gross in the first 3–5 years, potentially reaching 8%–12% gross as the corridor matures — versus Blue Area’s current 6%–10% gross on a much higher capital base.
- Capital Appreciation Trajectory: The G.T. Road strip’s strongest case is capital appreciation, not immediate yield. If the corridor follows the trajectory of G-9 Markaz (which traded at PKR 400K–PKR 600K/sq yd a decade ago and now clears at PKR 1.2M–PKR 1.7M/sq yd), early buyers at PKR 7.5 Lac–PKR 9 Lac/sq yd could see 2x–3x appreciation over a 7–10 year horizon.
Who Should Be Watching This Corridor — Corporate Developers, Logistics Operators, or Long-Horizon Investors?
| Buyer Profile | Corridor Fit | Recommended Plot Size | Primary Rationale |
|---|---|---|---|
| Corporate Developer (Mixed-Use) | Strong | 1,500–2,500 sq yd | FAR 1:6–1:8 enables retail-plus-office towers; 5–8 year development horizon |
| Automotive / Branded Retail Operator | Very Strong | 800–1,500 sq yd | 120,000+ daily vehicle count; immediate brand visibility on N-5 |
| Logistics / Cold-Chain Operator | Very Strong | 2,500–4,000 sq yd | Airport proximity (12–18 min), CPEC alignment, large-format warehousing |
| Hypermarket / Large-Format Retail | Strong | 2,000–3,000 sq yd | 500,000+ resident catchment within 15-min drive |
| HNWI / Long-Horizon Investor | Moderate | 500–1,000 sq yd | Capital appreciation play; 7–10 year horizon required for full value maturation |
| Short-Term Yield Investor | Weak | Any | Immediate rental yield will be below Blue Area; not suited for 2–3 year horizons |
For investors already tracking the Signature Rotana Islamabad on the Srinagar Highway — which sits within the same western Islamabad transit belt — the G.T. Road corridor represents the commercial land complement to that hospitality commercial case.
💡 Senior Property Advisor Insight — Muhammad Ali Dawood, MaxX Capitals: “The G.T. Road strip is not a Blue Area replacement — it is a Blue Area precursor. Investors who entered G-9 Markaz when it was a ‘highway strip’ are now sitting on 3x–4x appreciation. The question for G.T. Road is not whether it will appreciate, but whether your capital horizon is long enough to capture that appreciation cycle. If you need yield in 24 months, this is not your corridor. If you are building a 7–10 year commercial portfolio, the entry rate differential alone makes this worth serious analysis.”
Conclusion: A Credible Corridor With a Long Maturation Curve
The CDA commercial plot rates per square yard on the G.T. Road strip — benchmarked at PKR 7.5 Lac and potentially clearing at PKR 9 Lac–PKR 1.1M in competitive auction conditions — represent a structurally sound entry point for long-horizon commercial capital. The corridor is not a Blue Area replacement in the near term. It is a greenfield commercial spine with sovereign CDA title, national highway frontage, a 120,000+ daily vehicle count, and a 500,000+ resident catchment that will take 7–10 years to fully monetize.
The revenue model is credible: PKR 500 Billion is a conservative partial-area estimate, and the full-area model at the floor rate already yields PKR 907.5 Billion. The phased auction structure protects market absorption. The FAR framework enables genuine high-rise commercial development. And the historical precedent from G-9 Markaz and I-8 Markaz suggests that early-tranche buyers in CDA commercial corridors consistently outperform late entrants on capital appreciation.
The risks are equally real: litigation stays, encroachment clearance delays, infrastructure provisioning gaps, and the fundamental uncertainty that PKR 7.5 Lac is a feasibility benchmark rather than a confirmed floor. Investors who enter this corridor must do so with verified auction documentation, a 7–10 year capital horizon, and a clear-eyed understanding that immediate rental yield will not match Blue Area benchmarks.
For investors evaluating the full spectrum of commercial property opportunities in Islamabad — from established Blue Area assets to emerging corridor plays — the G.T. Road strip deserves serious analysis, not speculative excitement.
Ready to Navigate Your Next Property Decision?
Before committing booking money or signing any builder agreements, ensure your paperwork, approvals, and auction readiness are fully verified by an advisor who monitors CDA auction sessions directly.
Muhammad Ali Dawood
Official AdvisorFrequently Asked Questions
What is the expected starting price per square yard for CDA G.T. Road commercial plots?
The CDA's internal feasibility model benchmarks a starting rate of PKR 7,50,000 (PKR 7.5 Lac) per square yard for the G.T. Road commercial strip. This is a planning estimate, not a confirmed reserve price. The confirmed auction floor will be published in the official CDA auction notice approximately 30–45 days before the first tranche launch date.
Investors should model their feasibility at PKR 9 Lac–PKR 1.1M/sq yd to account for the bid premium typically observed at CDA auctions, where winning bids clear 15%–45% above the published reserve price.
How does PKR 7.5 Lac per sq yd on G.T. Road compare to current Blue Area commercial plot rates?
PKR 7.5 Lac/sq yd on G.T. Road represents a 65%–75% discount to Blue Area's current auction rates of PKR 2.2M–PKR 3.2M per square yard. The 3.5x rate differential reflects Blue Area's 30-year corporate tenant base, established FAR-enabled high-rise development, and central business district positioning — advantages the G.T. Road corridor will need 7–10 years to replicate.
The more relevant comparison is with I&T Centres (PKR 500K–PKR 850K/sq yd) and I-8 Markaz (PKR 900K–PKR 1.3M/sq yd), where G.T. Road's benchmark sits at a modest premium justified by national highway frontage and sovereign CDA title.
How did CDA calculate the Rs 500 billion to Rs 975 billion revenue projection for the G.T. Road strip?
The PKR 500 Billion figure is a conservative partial-area absorption model — approximately 55%–60% of the 1.21 million sq yd net developable area at the PKR 7.5 Lac floor rate. At full-area disposal, the PKR 7.5 Lac floor rate alone generates PKR 907.5 Billion. The PKR 975 Billion upper estimate reflects a blended rate of approximately PKR 8.1 Lac/sq yd across the full net area — achievable if first-tranche plots clear above reserve, as historical CDA auction data consistently shows.
What plot sizes will CDA offer in the G.T. Road commercial auctions and which size suits which business type?
CDA's design committee is finalizing plot dimensions ranging from 500 sq yd to 4,000 sq yd. Small plots (500–800 sq yd) suit petrol stations, fast-food outlets, and single-brand showrooms. Mid-range plots (800–1,500 sq yd) suit car dealerships and retail plazas. Large plots (1,500–4,000 sq yd) suit hypermarkets, logistics hubs, and mixed-use commercial towers.
The 800–1,500 sq yd range is expected to attract the most competitive bidding, as it balances accessible capital requirements with sufficient FAR leverage for viable commercial development.
What are the payment terms for CDA commercial plot auctions — is there an installment option?
CDA commercial auctions do not offer traditional installment plans. The structure is milestone-based: 25% within 30 days of bid acceptance (which unlocks building plan submission rights), with the remaining 75% due at possession. There is no monthly installment option — buyers must have the full capital available within the possession timeline.
An advance payment rebate of 5% is available for buyers who pay 100% within 30 days of bid acceptance, reducing the effective cost for cash-ready buyers.
What does the 5% USD rebate clause in CDA auction terms mean for overseas Pakistani buyers?
Overseas Pakistani buyers who remit the full winning bid amount in US Dollars (USD) through official SBP-approved banking channels receive a 5% discount on the total bid amount. This is stackable with the 5% advance payment rebate, giving USD-paying overseas buyers a maximum combined discount of 10% off the winning bid price.
For a PKR 2 Billion winning bid, this combined discount saves PKR 200 Million — a material incentive for overseas investors with USD-denominated capital. Remittance must comply with State Bank of Pakistan foreign currency remittance regulations.
How many auction tranches will CDA release for the G.T. Road corridor and over what timeframe?
CDA plans to release G.T. Road commercial plots in 3 to 5 structured tranches over multiple years — modeled on the New Blue Area (G-9/F-9) phased auction methodology. No confirmed tranche schedule has been published as of 2026. The first tranche is expected after the design committee finalizes plot demarcation, encroachment clearance is completed, and the official auction notice is gazetted.
Investors should monitor CDA's official website and the Jinnah Convention Centre auction calendar for confirmed tranche announcements.
What FAR ratio is expected for commercial plots on the G.T. Road strip and how does it affect development feasibility?
G.T. Road strip plots are expected to qualify for FAR ratios of 1:4 to 1:10+ depending on plot size and frontage. Small plots (500–800 sq yd) will likely receive FAR 1:4–1:5. Large highway-frontage plots (2,500–4,000 sq yd) may qualify for FAR 1:8–1:10+, enabling 18–45+ storey developments where soil conditions permit.
At FAR 1:6 on a 1,500 sq yd plot, the developer can build approximately 13,500–15,000 sq ft of gross leasable area — sufficient to generate PKR 6M–PKR 10M/month in commercial rental income from a well-tenanted mixed-use development.
Is the PKR 7.5 Lac per sq yd rate a confirmed reserve price or a feasibility estimate that could change before the auction?
PKR 7.5 Lac per sq yd is a CDA internal feasibility model benchmark — not a confirmed reserve price. The confirmed reserve price will be set by CDA's Finance and Planning wings closer to the first tranche launch and published in the official auction notice. It could be higher or lower than PKR 7.5 Lac depending on market conditions, infrastructure readiness, and CDA's revenue targets at the time of launch.
Investors must not make capital commitments, sign any agreements, or pay any booking amounts based on this figure alone. Any party claiming to offer pre-launch bookings or file allotments at PKR 7.5 Lac/sq yd is operating without CDA authorization.
Join The Discussion